Spa Slipper OEM Financial Stability Assessment for Europe RFQs
By Vincent Xi, Editorial Author
For a manufacturing RFQ in Europe, a spa slipper OEM financial stability assessment should end in a documented release, conditional release, or hold before the buyer pays a deposit, authorizes material purchasing, or reserves production capacity. The assessment applies only to the specified spa slipper order and contracting structure. It does not rate a named supplier, prove solvency, or replace product-compliance, contract, tax, insolvency, or country-specific legal review.
Start by reconciling the legal contracting entity, invoice issuer, production-site role, and bank beneficiary. Then confirm that financial records cover the relevant entity and comparable periods, test how the order will fund materials and work in progress, freeze the quoted product scope, and calculate the buyer’s preproduction cash exposure.
The cited pages provide contextual inputs rather than evidence of any particular OEM’s financial condition. The controls below are buyer-defined procurement controls, not statutory requirements, certifications, or universal financial thresholds.
Author basis: The Vincent Xi author profile identifies Vincent Xi as Editorial Author. No factory-visit, product-test, certification, client-outcome, or manufacturing-experience claim is made.
Europe RFQ gates for a spa slipper OEM financial stability assessment
Apply the decision gate to the named quotation, purchase order, legal entity, beneficiary, and manufacturing arrangement. A favorable sample or low price must not override an unresolved identity or payment conflict.
| Decision | Evidence finding | Procurement action |
|---|---|---|
| Release | The contracting entity, invoice issuer, production role, and approved beneficiary reconcile. Financial records identify their entity, period, currency, source, and preparation or audit status. The order-funding bridge aligns with the frozen quotation. | Approve only the recorded quotation scope, purchase order, beneficiary, currencies, payment schedule, delivery basis, and validity period. |
| Conditional release | A defined non-identity evidence gap remains, but the next payment or production milestone can be prevented from progressing until it is closed. | Record the missing evidence, owner, due date, affected milestone, acceptance condition, and automatic hold trigger. Do not use this status for an unresolved entity or beneficiary mismatch. |
| Hold | Entity or beneficiary data conflict, documents cannot be authenticated, periods are not comparable, the funding explanation remains materially incomplete, or exposure exceeds the buyer’s approved limit. | Do not pay a deposit, authorize material purchasing, or reserve further capacity. Correct the evidence and repeat the affected review. |
Within this buyer-defined framework, an unresolved legal-entity or bank-beneficiary mismatch is a hard stop. Hotemax discusses full advance-payment requests as a supplier-audit warning sign. That supports escalation and exposure analysis, but it does not prove insolvency or establish a universal payment rule (Hotemax).
Practical RFQ checklist for spa slipper manufacturing in Europe
Send this checklist with the RFQ and retain the completed version in the approval file. For each item, record Complete, Open, or Not applicable, plus the evidence filename, evidence date, entity scope, currency where relevant, verification route, reviewer, owner, due date, and effect on the release decision. Corporate-identity and beneficiary checks must not be marked Not applicable, and verbal assurances do not close an evidence item.
- [ ] Lock the RFQ control header. Supplier return: Quote reference, issue date, validity period, quotation currency, payment currency, delivery basis, assumptions, and exceptions. Buyer check: Match the response to the buyer entity, European delivery country, demand period, approved specification, and internal approval file.
- [ ] Reconcile corporate identity and operating roles. Supplier return: Local-language legal name, registration identifier, registered address, authorized-signatory evidence, and the roles of the contracting company, exporter, production site, and related entities. Buyer check: Verify registration information through an independent route and reconcile identifiers across the quote, contract, invoice, bank evidence, financial records, and factory relationship.
- [ ] Verify the bank beneficiary independently. Supplier return: Beneficiary legal name, bank details, payment currency, bank-reference evidence where available, and an explanation of any collection-account or related-party arrangement. Buyer check: Verify the account through contact details obtained independently of the payment instruction. Hold payment until every mismatch is resolved and documented.
- [ ] Index the financial records. Supplier return: Balance sheet, profit-and-loss statement, cash-flow statement, and current management accounts for the buyer-selected periods, with entity scope, period end, currency, accounting basis, preparation or audit status, issue date, and source. Buyer check: Compare records only when their entity and periods are compatible. Do not use group figures as evidence for the contracting entity unless the relationship and available financial support are documented.
- [ ] Review cash, working capital, and debt. Supplier return: Operating cash-flow information, receivables and payables ageing, inventory position, debt schedule, maturity information, secured obligations where disclosed, and documented available facilities. Buyer check: Test whether the explanation for material purchasing and work in progress is consistent with the records and proposed payment terms. SupplierAlly discusses registered capital, debt-to-equity, profitability, and cash flow as review inputs (SupplierAlly).
- [ ] Obtain independent corroboration. Supplier return: Consent and exact entity identifiers for buyer-ordered credit information, bank-reference verification, and trade-reference contact. Buyer check: Record the evidence date, entity scope, order context, and verification route. Hotemax discusses credit reports, bank-reference letters, and trade references in its supplier-audit context (Hotemax).
- [ ] Complete the order-funding bridge. Supplier return: A schedule showing when upper, insole, outsole, packaging, labor, and other order costs arise; what the deposit funds; what the supplier funds; and what documented financing is available to the contracting entity. Buyer check: Reconcile the schedule with the quote, production plan, financial records, and payment milestones. Treat an unexplained funding gap as an open release condition.
- [ ] Freeze the quoted spa slipper scope. Supplier return: Spa slipper specification, quantity, release pattern, production basis, packaging, inspection and testing scope, quotation currency, delivery basis, cost inclusions, exclusions, and change-control terms. Buyer check: Require a corrected quotation when a required material, process, packaging, inspection, testing, logistics, tax, setup, or other cost element is missing or unclear.
- [ ] Validate the demand basis. Supplier return: Requested quantity, delivery pattern, forecast assumptions, inventory policy, and replacement inputs supplied or approved by the buyer. Buyer check: Test order size against buyer records. Hotel News Resource discusses treatment-room occupancy, laundry, storage, replacement, waste, and occupied-treatment-room cost as operating variables, but it does not establish the quantity or price for this RFQ (Hotel News Resource).
- [ ] Confirm production continuity and change control. Supplier return: Production-site legal name and role, material subcontractors, proposed subcontracting, raw-material plan, work-in-progress reporting, site-change controls, and contingency route. Buyer check: Hold the affected milestone if an unapproved production site, subcontractor, material, bank account, process, or schedule is introduced.
- [ ] Calculate deposit and preproduction exposure. Use the complete verified quotation and payment schedule, compare the result with the buyer’s approved exposure limit, and identify the evidence required before each payment or production milestone. Do not deduct unauthenticated guarantees, verbal refund promises, or unverified references.
- [ ] Route the file to the correct European review. Identify whether the buyer and delivery file concerns an EU member state, an EEA jurisdiction outside the EU, the UK, or another country-specific European route. Record the applicable local finance or legal owner instead of transferring a conclusion from another jurisdiction.
- [ ] Issue the final gate record. Record the reviewed legal entity, approved beneficiary, document dates, quotation reference, frozen specification, calculated exposure, open conditions, due dates, stop-payment triggers, and procurement, finance, and quality approval owners. State release, conditional release, or hold.
SupplierAlly’s page is framed around Chinese OEM credit risk. It may inform origin-specific source selection when relevant, but it does not establish the condition of a named supplier or create a financial rule for European buyers. Supplier origin must be documented separately from the European sales-market and delivery file.
Europe procurement-file separation for the RFQ
The cited financial-risk sources do not establish a Europe-wide legal, payment, tax, or insolvency rule. EU, EEA, UK, and country-specific records should therefore remain distinct in the approval file.
| File category | Information to record | Control boundary |
|---|---|---|
| EU buyer file | Exact buyer entity, EU member state, delivery country, quotation and payment currencies, and local finance or legal approval owners. | Separate EU-level considerations from member-state procedures and verify the applicable national requirements before release. |
| EEA buyer outside the EU | Exact buyer entity, applicable EEA jurisdiction, delivery country, currencies, and local approval route. | Label the file separately rather than treating it as an EU member-state file. |
| UK buyer file | UK contracting entity, delivery location, currencies, and UK-specific approval owners. | Maintain a separate review. Do not treat an EU or EEA approval record as evidence that UK requirements have been satisfied. |
| Country-specific European delivery file | Delivery country, buyer or importing entity, delivery basis, currencies, local review owner, and required supplier documents. | Do not transfer a legal, financial, tax, or payment conclusion from another European jurisdiction without verification. |
| Supplier incorporation and production file | Contracting-entity jurisdiction, production-site jurisdiction, exporter role, registry route, bank jurisdiction, and relationships among the entities. | Verify origin-specific corporate and banking evidence separately from the European buyer-market classification. |
State the quotation currency, payment currency, price-validity period, delivery basis, and any proposed exchange-rate or raw-material adjustment mechanism. Do not infer a currency or payment practice from the word Europe.
Assess financial stability without inventing a supplier score
SupplierAlly discusses debt-to-equity, profitability, cash flow, third-party information, and changes in payment terms. Hotemax discusses debt, margins, references, credit information, and advance-payment risk. The measures below translate those contexts into buyer-defined RFQ tests. They do not create universal pass marks or a composite supplier score.
| Measure | Buyer-defined calculation or test | Decision use |
|---|---|---|
| Entity reconciliation | Confirm that the approved legal name and registration identifier reconcile across registration, quote, contract, invoice, beneficiary, production-site, and financial evidence. | Any unresolved contracting-entity or beneficiary conflict produces a hold. |
| Quoted purchase-order value | Accepted quantity multiplied by verified unit price, plus accepted setup, packaging, inspection, testing, logistics, and other line items, less documented credits. | Establish the complete amount whose funding and payment exposure must be assessed. |
| Preproduction cash exposure | Payments due before accepted release evidence, less only the buyer-confirmed recoverable amount under the signed contract or approved payment instrument. | Compare the result with the buyer’s approved exposure limit. Do not subtract a verbal refund promise, unauthenticated guarantee, or unverified reference. |
| Order-funding gap | Documented preproduction cash outlays for the quoted order, less the supplier-funded amount and documented available financing attributable to the contracting entity. | Investigate a positive unexplained gap rather than assuming registered capital is available to fund the order. |
| Debt-to-equity review | Apply the buyer’s documented definition of debt divided by equity for the same entity, reporting period, and currency basis. | Review the trend and explanation. Do not apply an uncited cutoff or force a ratio when the denominator makes the result non-interpretable. |
| Operating cash-flow review | Compare reported operating cash flow across compatible periods and reconcile material changes with management accounts and the order-funding bridge. | Request updated evidence when deterioration or inconsistency is not adequately explained. |
| Payment-term change review | Compare the proposed milestone schedule with the approved quote and documented negotiation history. | Repeat the financial approval when a material change increases exposure, changes the beneficiary, or moves payment ahead of evidence. |
Illustrative spa slipper RFQ deposit exposure
Every exact value below is an example buyer assumption for the same illustrative purchase order as of its RFQ issue date. The values are not market averages, supplier capabilities, price benchmarks, or recommended payment terms. Replace them with approved buyer data and verify them in the supplier quotation and contract.
| Illustrative input | Unit, scope, date context, and source status |
|---|---|
| Demand quantity | 24,000 pairs for the single illustrative spa slipper purchase order covering the buyer-assumed 12-month period beginning on the RFQ issue date; example buyer assumption, not source-derived, to replace with approved operating and inventory data and verify in the supplier quote. |
| Unit price | €1.20 per pair for the same single illustrative purchase order as of the RFQ issue date; example quote assumption to verify against specification, packaging, delivery basis, freight, taxes, setup, inspection, testing, exclusions, and price validity. |
| Deposit term | 25% of the same illustrative purchase-order value as of the RFQ issue date; example payment assumption to verify in the quotation and signed contract rather than a stated market norm. |
The resulting example calculations are:
- 24,000 pairs × €1.20 per pair = €28,800 for the same single illustrative purchase order as of the RFQ issue date. This is an example calculation to verify against the complete supplier quotation.
- €28,800 × 25% = €7,200 of illustrative initial deposit exposure for that same purchase order as of the RFQ issue date. This is an example calculation to verify against the signed payment schedule and any additional preproduction amounts.
Compare the calculated deposit exposure with the buyer’s approved limit, the evidence required at each milestone, material recoverability, replacement-stock position, replacement lead time, and the operational effect of delay. A full advance-payment request should trigger additional review, not an automatic conclusion about solvency (Hotemax).
Demand should come from the buyer’s operating and inventory records. The Hotel News Resource page supplies relevant spa operating context, but it is not used to derive the illustrative quantity, unit price, or deposit term (Hotel News Resource).
Freeze the spa slipper scope before financial approval
The following values are additional example buyer specification assumptions for the same illustrative purchase order as of its RFQ issue date. They are not standards, certifications, market norms, or SlipperForge manufacturing capabilities. Verify each value in the supplier quote and approved sample.
| Specification variable | Illustrative RFQ assumption | Buyer verification | Financial relevance |
|---|---|---|---|
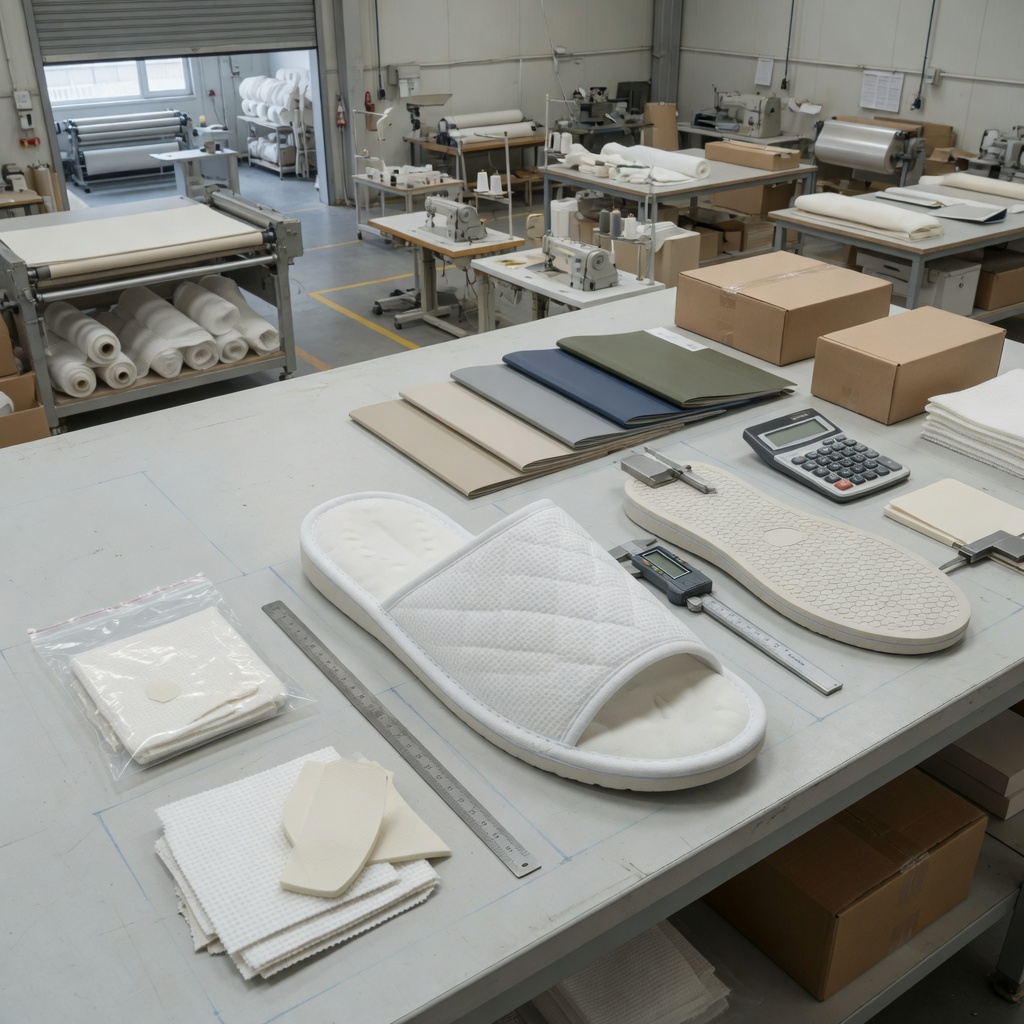
| Overall length | 28.0 cm overall length with a ±0.5 cm buyer tolerance for the illustrative adult open-toe spa slipper in the same single purchase order as of the RFQ issue date; example buyer assumption to verify in the supplier quote and approved sample. | Measure heel to toe with the sample flat and record the sample identifier and measuring instrument. | A dimensional change can alter material consumption, packaging fit, and quote comparability. |
| Maximum forefoot width | 11.0 cm maximum forefoot width with a ±0.3 cm buyer tolerance for the same illustrative spa slipper as of the RFQ issue date; example buyer assumption to verify in the supplier quote and approved sample. | Measure at the buyer-defined widest forefoot point without compressing the upper. | A width change can affect upper and sole material requirements. |
| EVA outsole thickness | 5.0 mm nominal pale EVA outsole thickness with a ±0.5 mm buyer tolerance for the same illustrative spa slipper as of the RFQ issue date; example buyer assumption to verify in the supplier quote and approved sample. | Measure at the buyer-defined outsole location and state whether tread relief is included or excluded. | A thickness or material change can affect cost, funding needs, packing, and quote scope. |
| Construction | White polyester waffle upper, foam insole, and pale EVA outsole as an example buyer construction assumption for the same RFQ-date sample. | Require a supplier material declaration, approved physical sample, and written approval for alternatives. | An unpriced substitution can invalidate cost and order-funding comparisons. |
The quotation should also identify dimensional measurement points, permitted material alternatives, color, edge finish, sole texture, packaging, carton configuration, sample and setup costs, inspection scope, testing scope, freight, taxes, delivery basis, and change-control terms. A lower quoted price does not demonstrate financial sustainability if required parts of the frozen spa slipper scope are excluded.
Product-sample approval must not override a financial or beneficiary hold. Financial release likewise does not constitute product-quality or compliance approval.
Reopen the assessment when payment or manufacturing changes
| Trigger | Required control |
|---|---|
| The quote, registration record, contract, invoice, production evidence, or financial records identify different entities | Document every entity’s legal name, identifier, jurisdiction, and role. Hold contracting and payment until the relationships are independently verified. |
| The beneficiary differs from the approved contracting entity or bank details change after approval | Hold payment and repeat beneficiary verification through an independently obtained contact. Require documented approval for any related-party collection arrangement. |
| Financial records use inconsistent entities, periods, currencies, accounting bases, or balances | Request a reconciliation and corrected document index. Do not calculate trends or ratios from incomparable records. |
| Cash flow, profitability, debt, or payment terms change materially without an authenticated explanation | Obtain updated records, repeat the funding and exposure calculations, and issue a revised release, conditional release, or hold decision. SupplierAlly discusses these factors in its OEM risk context (SupplierAlly). |
| Registered capital is presented as the sole evidence of stability | Request current cash-flow, working-capital, debt, facility, and order-funding evidence. Treat registered capital only as the registration input described in the cited context. |
| A full advance payment is requested | Quantify the full amount at risk, request the documented funding reason, and assess buyer-approved milestone or payment-instrument controls before release (Hotemax). |
| Required material, packaging, inspection, testing, delivery, or setup scope is omitted | Require a complete requote against the frozen spa slipper specification and recalculate purchase-order exposure. |
| A material, subcontractor, production site, schedule, or manufacturing process changes | Hold the affected milestone until specification, price, funding, continuity, and exposure effects are reapproved. |
The final approval record should identify the reviewed legal entity, approved beneficiary, document dates, quotation reference, frozen specification, calculated preproduction exposure, open conditions, stop-payment triggers, and procurement, finance, and quality approval owners.
Source contexts, methodology, and limitations
| Cited source | Context used | Boundary applied |
|---|---|---|
| Hotemax | Hotel-supplier audit context covering trade references, credit information, bank-reference letters, debt, margins, and advance-payment concerns. | It does not prove that a particular OEM is stable or insolvent and does not establish a universal payment threshold. |
| SupplierAlly | Chinese OEM credit-risk context covering business registration, registered capital, debt-to-equity, profitability, cash flow, external information, and payment-term changes. | Registered capital is not treated as available order cash, and no ratio is treated as a certification or universal pass mark. |
| Hotel News Resource | Spa operating context covering treatment-room occupancy and variables such as laundry, storage, replacement, waste, and occupied-treatment-room cost. | It is not used as a supplier financial statement, European demand benchmark, price benchmark, or source for the illustrative RFQ values. |
| Vincent Xi author profile | Author name and Editorial Author role. | No manufacturing credential, factory experience, test history, certification, or customer outcome is inferred. |
Methodology: The cited statements were limited to their stated source contexts and translated into buyer-defined entity, beneficiary, financial-scope, cash-flow, debt, corroboration, order-funding, quote-scope, continuity, and payment controls. Numerical values were isolated as illustrative RFQ-date assumptions. The calculations show how order quantity, verified unit price, and payment terms convert into purchase-order and deposit exposure. No composite supplier score or universal ratio threshold is used.
Limitations and items to verify:
- The cited pages are contextual editorial or practitioner sources. They are not audited financial statements, registry extracts, bank confirmations, legal opinions, or product-compliance documents for a named OEM.
- Confirm each cited page’s publication or update date, record an access date, and check its current relevance before using it in a live procurement file.
- Verify every supplier document’s legal entity, registration identifier, issue date, reporting period, currency, accounting basis, preparation or audit status, source, scope, and authenticity.
- Replace every illustrative quantity, price, payment term, dimension, tolerance, and material description with buyer-approved data and supplier-quoted terms for the dated RFQ.
- Verify EU, EEA, UK, and country-specific legal, tax, payment, insolvency, and enforcement requirements for the exact buyer, supplier, bank, and delivery jurisdictions.
- A registry, credit, bank, trade-reference, or financial document supports only its stated entity, scope, date, and status. It must not be presented as certification or proof of financial stability beyond that evidence.
- Financial release remains separate from product-quality, contractual, and applicable compliance approval.
Discuss Your Requirements
Review our manufacturing capabilities, then share your specifications for a supplier-fit review.